Can an administration that has built its political identity on rejecting dependence explain a public debt that has swelled by close to 4,000 billion FCFA in a little over five years? That is the awkward question now confronting Burkina Faso’s authorities, and it sits at the centre of the country’s economic debate.
Ibrahim Traoré has made self-reliance a founding element of his message. He states repeatedly that Burkina Faso must count on its own strength, and that the country does not need to borrow in order to construct its development. The doctrine is presented as a clean break with past practice: reduced external dependence, reinforced economic sovereignty, and the ambition to finance development out of national resources.
Yet the trajectory of public debt argues for greater caution regarding that claim. Behind the political narrative, an accounting reality has taken hold: Burkina Faso’s public debt has risen sharply in recent years.
From under 5,000 billion to more than 8,700 billion FCFA
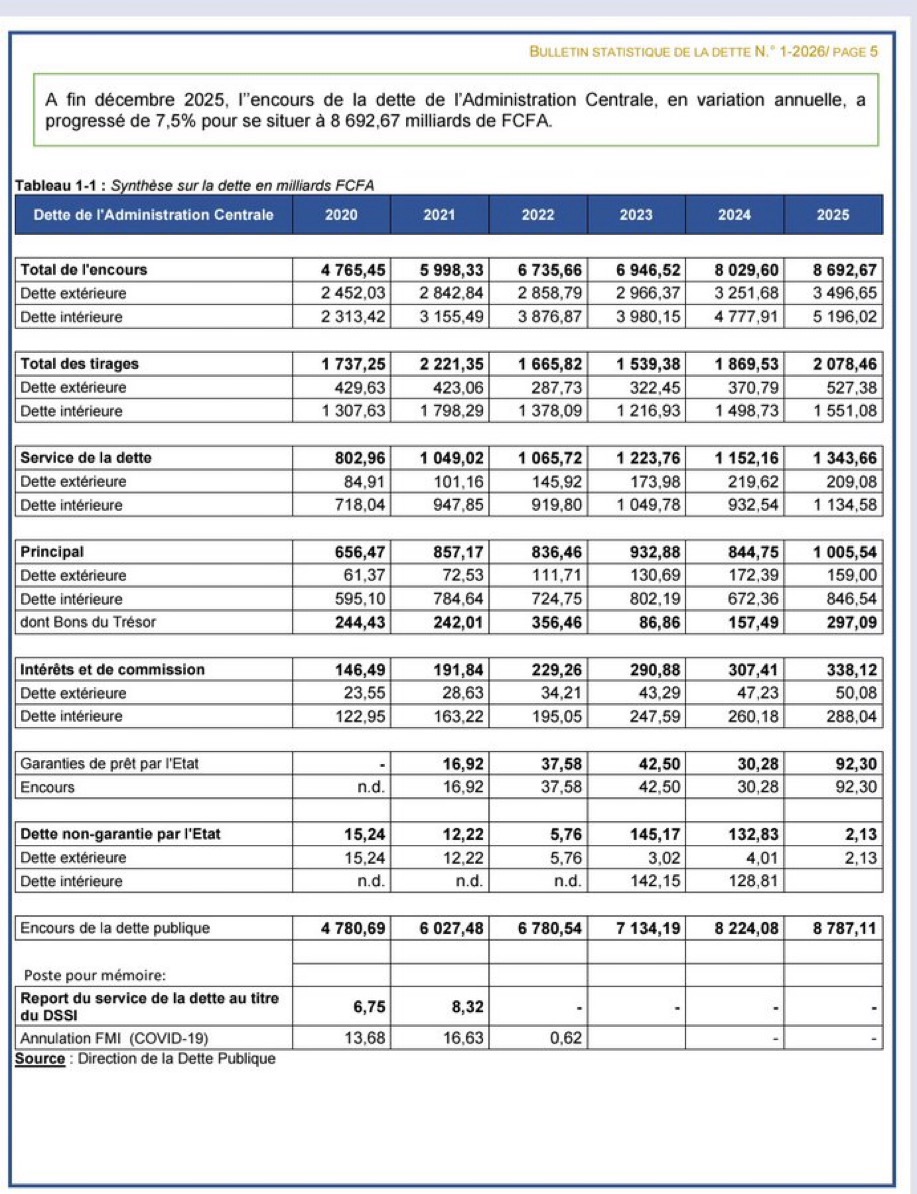
At the close of December 2020, the outstanding debt of central government stood at 4,765.45 billion FCFA. By the end of 2021 it had already climbed to approximately 6,107 billion FCFA, on the basis of figures produced by the ministry of economy and finance.
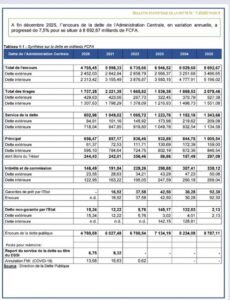
The upward movement has continued without interruption. According to the most recent statistical bulletin of the Burkinabè treasury, outstanding central government debt reached 8,692.67 billion FCFA at the end of December 2025. A few months later, at the end of March 2026, it stood at 8,731.5 billion FCFA.
In short, over the space of a few years Burkina Faso has moved from an indebtedness level below 5,000 billion FCFA at the end of 2020 to more than 8,700 billion in 2026.
The genuine issue is not whether a state borrows
The difficulty is not simply determining whether a state contracts debt. Public borrowing is not automatically synonymous with poor management. A state may borrow to build infrastructure, support investment, respond to a security crisis or sustain public spending when its revenue falls short.
The essential question is a different one:
- what purposes do the new loans serve;
- at what cost are they contracted;
- and what future repayment capacity do they generate?
The growing weight of domestic debt
The very structure of Burkina Faso’s debt warrants close attention. At the end of 2025, close to 60% of central government debt consisted of domestic debt, largely in the form of treasury bills and bonds. Domestic debt alone amounted to roughly 5,196 billion FCFA.
This trend matters all the more because domestic financing is not costless. The principal must be repaid, and interest must be paid alongside it. In the first quarter of 2026, debt service already reached 407.1 billion FCFA, an increase of 31.5% over a year.
Financial sovereignty also carries a price tag
Ibrahim Traoré is entitled to defend a policy of economic sovereignty. But sovereignty cannot be measured solely by the refusal of certain partners or by declarations of financial independence.
It is equally measured by a state’s ability to raise its revenue durably, keep its expenditure under control, finance its investments and contain the burden of debt service.
Mining wealth does not automatically translate into liquidity
Burkina Faso possesses considerable mining resources, gold in particular. Even so, the existence of those resources does not automatically mean the state commands sufficient liquidity to finance every ambition without turning to borrowing.
This is precisely where the debate deserves to be reframed. The real challenge is not to proclaim that Burkina Faso will not borrow, but to demonstrate that every franc borrowed produces enough value to justify its cost.
More than 8,700 billion FCFA: the answers the authorities still owe
The Burkinabè government may highlight its investments, its military effort, its infrastructure or its social policies. Those expenditures must nonetheless be weighed against the evolution of the debt.
The International Monetary Fund, in its 2026 analysis, classifies Burkina Faso at moderate risk of debt distress, while considering the debt sustainable over the medium term. The institution nevertheless identifies several vulnerabilities, notably the refinancing risk attached to domestic debt, dependence on gold export earnings and the security situation.
It would therefore be excessive to present this rise in debt mechanically as proof that Burkina Faso is insolvent. The available data do not permit such a conclusion.
But it would be equally difficult to maintain that the country has developed in recent years without significant recourse to borrowing.
The figures tell a different story. Between the end of 2020 and the first quarter of 2026, outstanding central government debt increased by nearly 4,000 billion FCFA.
The apparent contradiction that now demands a precise response
One question remains, simple in its formulation yet politically and economically decisive: if Burkina Faso does not need to borrow in order to build itself, how is the increase of several thousand billion FCFA in its public debt over this period to be explained?
It is on this apparent contradiction between the discourse of financial sovereignty and the evolution of the public accounts that the government of Ibrahim Traoré will have to provide specific answers: how much was borrowed, from whom, at what rate, to finance which projects, and with what measurable results for the population?
In matters of public finance, slogans can be seductive. The figures, for their part, remain to be explained.